
When you think about insurance, your mind immediately goes to the tangible coverages. The Collision coverage that protects your vehicle or the Dwelling coverage that is there to protect your home.
But what about those unexpected lawsuits where you could lose everything. How do you protect yourself from very bad things??

When a serious car accident happens or someone is injured at your home or rental property, the liability coverage on your auto, home and landlord policies will respond. But a serious claim can quickly exhaust those limits.
And then you’re left wondering:
What protects your assets when your underlying liability coverage runs out??
That’s where the Personal Umbrella comes in.
An Extra Layer of Protection
A Personal Umbrella provides excess liability coverage over your underlying policies, such as your home, auto, rental property and boat insurance.
Consider a serious at-fault car accident where multiple people are injured. Your auto liability coverage will respond, but with multiple injuries, medical expenses, lost wages and other damages, your underlying liability limit can be exhausted quickly.
That’s when your umbrella can provide another $1 million – or more – of liability protection. The same concept applies for serious liability claims at your home, your boat, rental property, and other exposures.
BY THE NUMBERS
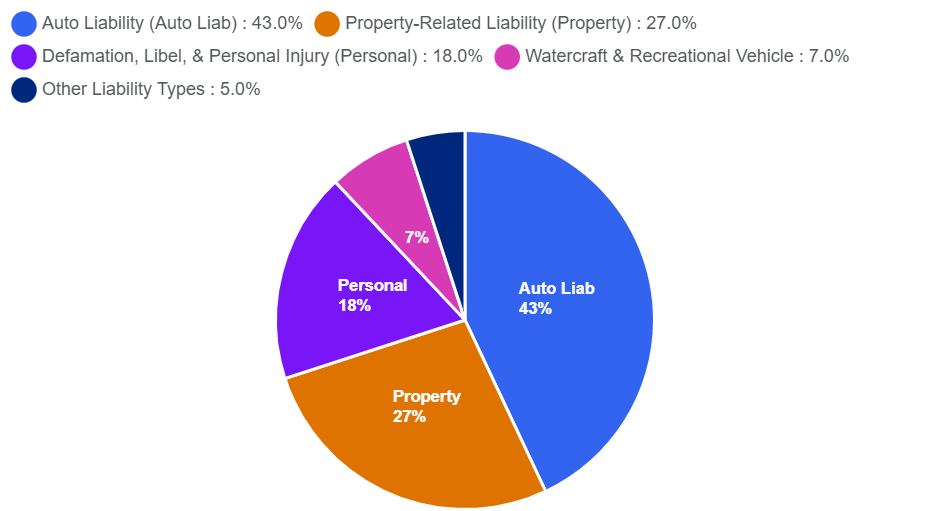
Liability losses can come from a number of different exposures. According to the Insurance Service Office (ISO) Claims Database, auto accidents account for the most umbrella claims with property related losses in a close second. Personal injury claims, including libel, slander, and defamation, round out the top three.
The take way is simple: serious liability claims can some from places you may not expect.
So, who needs an umbrella?
Easy…. anyone with something to protect – a home, savings, investments, retirement accounts or future earnings. Keep in mind that the more you own or the more you earn increases your odds of getting sued.
Your risk profile also matters. Do you have a youthful operator in the household? Own a rental property? Have a boat or jet ski? The more complex your risk profile, the more important it becomes to consider additional layers of liability protection.
Where you live can also play a role. If you live in an affluent community where wealth and property values are higher, it can increase your probability of getting sued. The zip code effect not only increases your odds of getting sued, it can also inflate the amount of damages that the injure parties are claiming.
How Much Umbrella Coverage is Enough?
Once you realize that you need an umbrella the next question is:
How much coverage do you need?
Limits are available in $1M increments with higher limits available up to $10M. It’s not a one size fits all answer. There are a several factors to consider when determining an appropriate limit.
Where to Start?
For many clients, $1 million is a starting point. But when you consider the potential cost of a serious liability claim, additional limits may make sense.
At J.J. Ruddy, our recommendations often start at $2 million depending on your individual circumstances and exposures.
Consider Your Asset Position
Your umbrella limit should be considered in relation to what you are protecting. That doesn’t mean your limit needs to match your asset value dollar for dollar, but it should give you a decent buffer to protect your asset position.
And Then There’s Peace of Mind
There is another benefit to a personal umbrella that doesn’t show up on a declarations page….peace of mind.
We don’t know when an accident will happen – or how serious it will be. Knowing you have another layer of liability protection in place can make a significant difference when something goes wrong. And sometimes it isn’t just about the coverage. It’s about being able to sleep at night.
Your Insurance Should Keep Up With Your Life
Assessing your liability exposure is part of our review process. We look at your assets, properties, vehicles, operators and activities that could create additional liability exposure. Just as important, we revisit those exposures to make sure that your coverage keeps up with your life changes.
Let us worry about what’s missing in your insurance coverage. Schedule a call to find out how your policies should work and bring clarity to your insurance program.
Looking Out for You Since 1909
For 117 years, J.J. Ruddy has been helping families protect the lives they’ve built and the people they love. We advocate, advise, and give our clients the confidence that their coverage is exactly where it should be.
If you know someone who would benefit from confidence in their coverage, please share our blog and we’ll take care of the rest.